Poland Revives Fuel Windfall Tax, Plans 60% Levy to Raise PLN 4 Billion
en.Wedoany.com Reported - On September 15, the Polish government revived its legislative plan to impose a temporary windfall tax on excess profits of fuel companies, planning to levy a 60% tax on fuel sales profits exceeding the benchmark level during the period from March 1 to December 31, 2026, with expected tax revenue of approximately PLN 4 billion. The funds will be used to support fuel price reductions and other price buffer measures for households and businesses. The bill was again placed on the agenda of the Polish Council of Ministers that day.
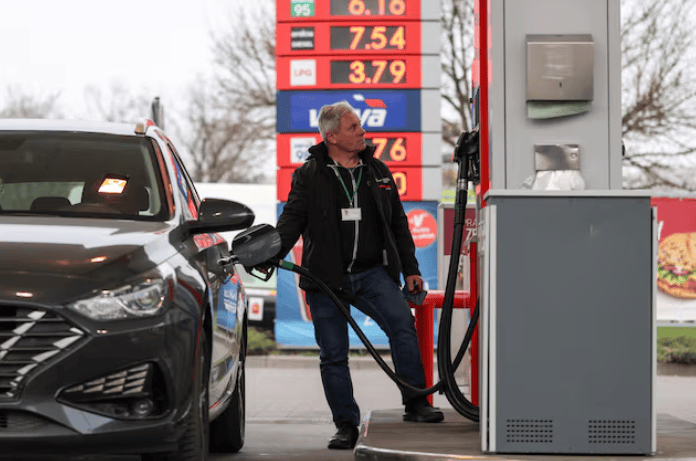
The tax is not levied on the entire profits of fuel companies. According to the calculation mechanism published by the Polish government, a company's fuel sales profit margin for 2026 will be compared with its average sales profit margin for 2025, and the 2025 profit margin will be raised by 20% to form a reference level. Only the portion exceeding this reference level enters the windfall tax base, at a rate of 60%. The tax mainly applies to companies engaged in the production, import, and intra-EU procurement of liquid fuels in Poland, as well as those holding relevant licenses for cross-border fuel trading. Heating oil and certain fuel blending operations are not within the scope of application.
According to the government's previous estimates, from March to December 2026, the companies concerned may generate approximately PLN 6.7 billion in taxable excess profits. At a 60% tax rate, the estimated tax revenue is approximately PLN 4 billion, of which approximately PLN 3.8 billion is planned to be paid in 2026, and the remaining approximately PLN 200 million will be settled in 2027. In its estimates, the government treated ORLEN, Poland's major refining and energy company, as one of the main market entities, while also including other fuel production and trading companies.
The tax is collected through a combination of advance payments and annual final settlement. The previous bill stipulated that the first advance tax payment covering March to July 2026 be divided into four equal installments, payable from September to December 2026, to avoid companies bearing the entire tax burden at once. Subsequent months follow a monthly advance payment mechanism, with final settlement after the end of the year.
The Polish government plans to use the relevant tax revenue for its fuel price buffer policy. The first phase of the previously implemented "CPN—Ceny Paliw Niżej" fuel price support program ran from March 31 to June 30, with the government lowering end-user prices through measures such as reducing fuel VAT and cutting excise duty. Data published by the Polish Ministry of Energy show that the fiscal cost of this round of measures was approximately PLN 4.7 billion, and the government originally planned to use windfall tax revenue to cover approximately 85% of the funding requirement.
This tax legislation had previously completed parliamentary procedures. The Polish Parliament passed the "Law on the Tax on Excess Profits from the Sale of Liquid Fuels from March to December 2026" on July 3, and the Senate subsequently amended provisions such as the tax burden cap, including stipulating that the windfall tax shall not exceed the income under the corporate income tax basis or the corresponding accounting profit.
On July 24, the Polish President referred the bill to the Constitutional Court for preventive review. The main controversy concerns the fact that the bill taxes profits generated from March 2026, while the relevant law completed its legislative procedure only afterwards, raising issues of retroactive application. Before the Constitutional Court issues its ruling, the July version of the bill cannot be signed by the President and formally take effect.
On September 15, the Polish government again placed the bill on the tax on excess profits from fuel sales from March to December 2026 on the agenda of the Council of Ministers. This renewed push still follows the core mechanisms of a 60% tax rate, a reference benchmark based on the 2025 average profit margin raised by 20%, and estimated revenue of approximately PLN 4 billion, with the funds continuing to be linked to fuel price buffer measures.
Related Products

40.5kV-1100kV Gas Insulated Metal-Enclosed Switchgear (GIS)
Henan Pinggao Electric Co., Ltd.
Oil-immersed Amorphous Alloy Core Distribution Transformer
Pinggao Group Smart Electric Co., Ltd.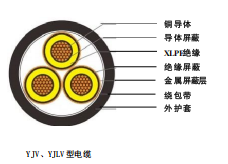
Rated Voltage 6-35kV Cross-linked Polyethylene Insulated Power Cable
TONGDING INTERCONNECTION INFORMATION CO., LTD.
Bidirectional Metal Hard Sealed Seawater Butterfly Valve
Henan Quanshun Flow Control Science & Technology Co., Ltd.
Manufacturer Direct Sales Tesla New Energy Electric Vehicle Universal DC 180kW Dual-gun Charging Pile Commercial Fast Charger
Anhui Haidira Electric Technology Co., Ltd.