Indonesian Thermal Coal Prices at Indian Ports Hit Four-Year High in September 2026
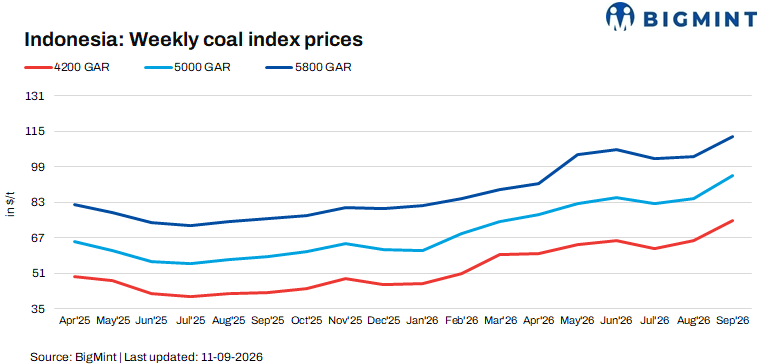
en.Wedoany.com Reported - Indonesian thermal coal prices in the Indian port market rose sharply week-on-week during the assessment week ending September 11, 2026. Both 4,200 GAR (Gross As Received) and 5,000 GAR prices touched four-year highs, primarily supported by tightening Indonesian supply, reduced cargo availability, and active Chinese buying interest. Supply-side constraints strengthened sellers' bargaining power, while elevated replacement costs and firm freight rates provided additional support to Indian prices.
BigMint vessel lineup data shows that Indonesia's non-coking coal exports fell to 26.95 million tonnes (mnt) in August 2026, down 16.1% from 32.11 mnt in the same period last year and down 5.7% from 28.59 mnt in July. Monthly exports had been relatively stable at around 28-29 mnt from April to July; this decline reflects tighter production controls and stricter export regulation, with reduced export supply supporting miners' offers and limiting spot cargo availability in the seaborne market.
On prices, 5,000 GAR rose by INR 300/t week-on-week to approximately INR 11,900/t at Kandla and approximately INR 11,800/t at Vizag, touching four-year highs, supported by tightening Indonesian supply and limited spot cargo availability. 4,200 GAR posted a larger gain, rising by INR 400/t to approximately INR 10,000/t at Kandla and approximately INR 9,900/t at Vizag, also at around four-year highs. 3,400 GAR at Navlakhi rose by INR 250/t to approximately INR 8,000/t, hitting a record high since this assessment began, driven by strong demand for this cost-competitive grade amid constrained Indonesian supply. Market participants noted that 3,400 GAR remains the most preferred grade due to its cost competitiveness, with procurement volumes of approximately 7,000-8,000 tonnes/day. Expectations of relatively stable Chinese demand ahead of the October Golden Week also provided some support to market sentiment.
On inventories, thermal coal stocks at major Indian ports rose marginally by 0.6% week-on-week in Week 36, from 13.40 mnt in Week 35 to 13.48 mnt. The increase was mainly driven by stockpiling at Mundra, Dhamra, and Tuticorin, while several other ports saw declines. Cautious procurement at high price levels prevented a larger build-up in port inventories. As of September 9, domestic coal-fired power plant inventories fell by approximately 7% week-on-week to 25.8 mnt, equivalent to only about 8 days of consumption, with nearly 59 plants reporting critical stock levels. Despite relatively cautious spot procurement, tightening domestic coal supply kept replacement costs for imported coal elevated.
The broader Indonesian market also remained supported. 4,200 GAR FOB (Free On Board) prices recorded the strongest weekly gain of approximately $5-6/t, 3,400 GAR rose by approximately $1-2/t, and 5,800 GAR prices were broadly stable. Firm Indonesian benchmark prices, combined with reduced export supply, indicate that Indian port prices continue to receive supply-side support.
Indonesian thermal coal prices at Indian ports are expected to remain firm with a mild upward bias in the near term, supported by constrained Indonesian supply, limited spot cargo availability, low domestic power plant inventories, and firm replacement costs. Continued Chinese procurement could further tighten seaborne supply. However, current high prices are beginning to limit buyer participation, with market participants reporting reduced spot transactions and buyer resistance to high-priced procurement. Supply constraints should prevent significant price corrections, but limited buying interest and affordability concerns may cap further gains.
Related Products

Oil-immersed Amorphous Alloy Core Distribution Transformer
Pinggao Group Smart Electric Co., Ltd.
Perfluorinated Ionic Membrane-CM-10N Series Membrane
Guizhou Juneng Century Technology Co., Ltd
KYN61-40.5 Indoor AC Metal-clad Removable Switchgear
Chongqing Transformer Co., Ltd.
IGBT Hydrogen Production Power Supply - High Power Air Cooling
Beijing Zhengzhuo Engineering Technology Co., Ltd.
6kV-35kV Medium and High Voltage Direct-Connected Energy Storage System
Hainan Jinpan Smart Technology Co., Ltd.
FR2000H 2.15MWh (Air-cooled) 20-foot Containerized Energy Storage System
Jiangyin Furen High-tech Co., Ltd.